18/10/2026
True diamonds require rigorous appraisal. A VND 5,400 billion project in the core CBD of Ho Chi Minh City is no different — and the dossier for this de-risked asset is fully prepared for your due diligence.
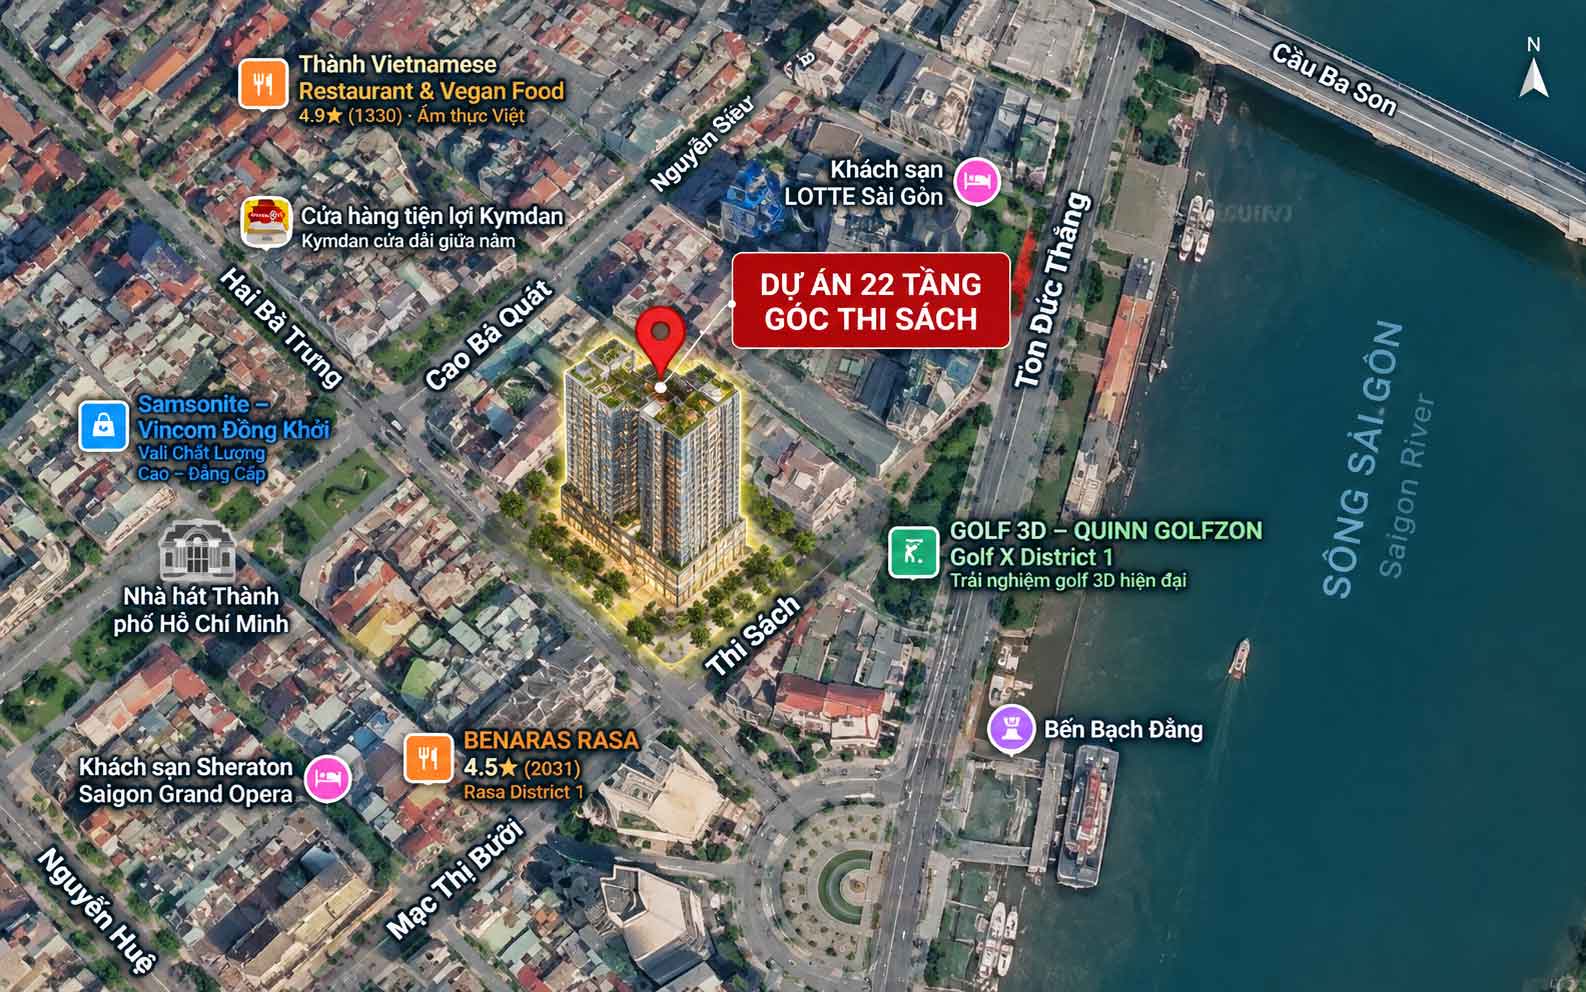
Achieve Realty VN is officially authorized to facilitate the 100% equity transfer of a Special Purpose Vehicle (SPV) owning a 3-basement, 22-story residential development at the dual-frontage corner of Thi Sach and Nguyen Sieu streets. Positioned in the heart of Little Japan, Saigon Ward (former District 1), the project has completed its structural framework, comprising 162 freehold apartments and 157 car parking spaces. Transfer price: VND 5,400 billion, inclusive of transaction taxes and turnkey legal status.
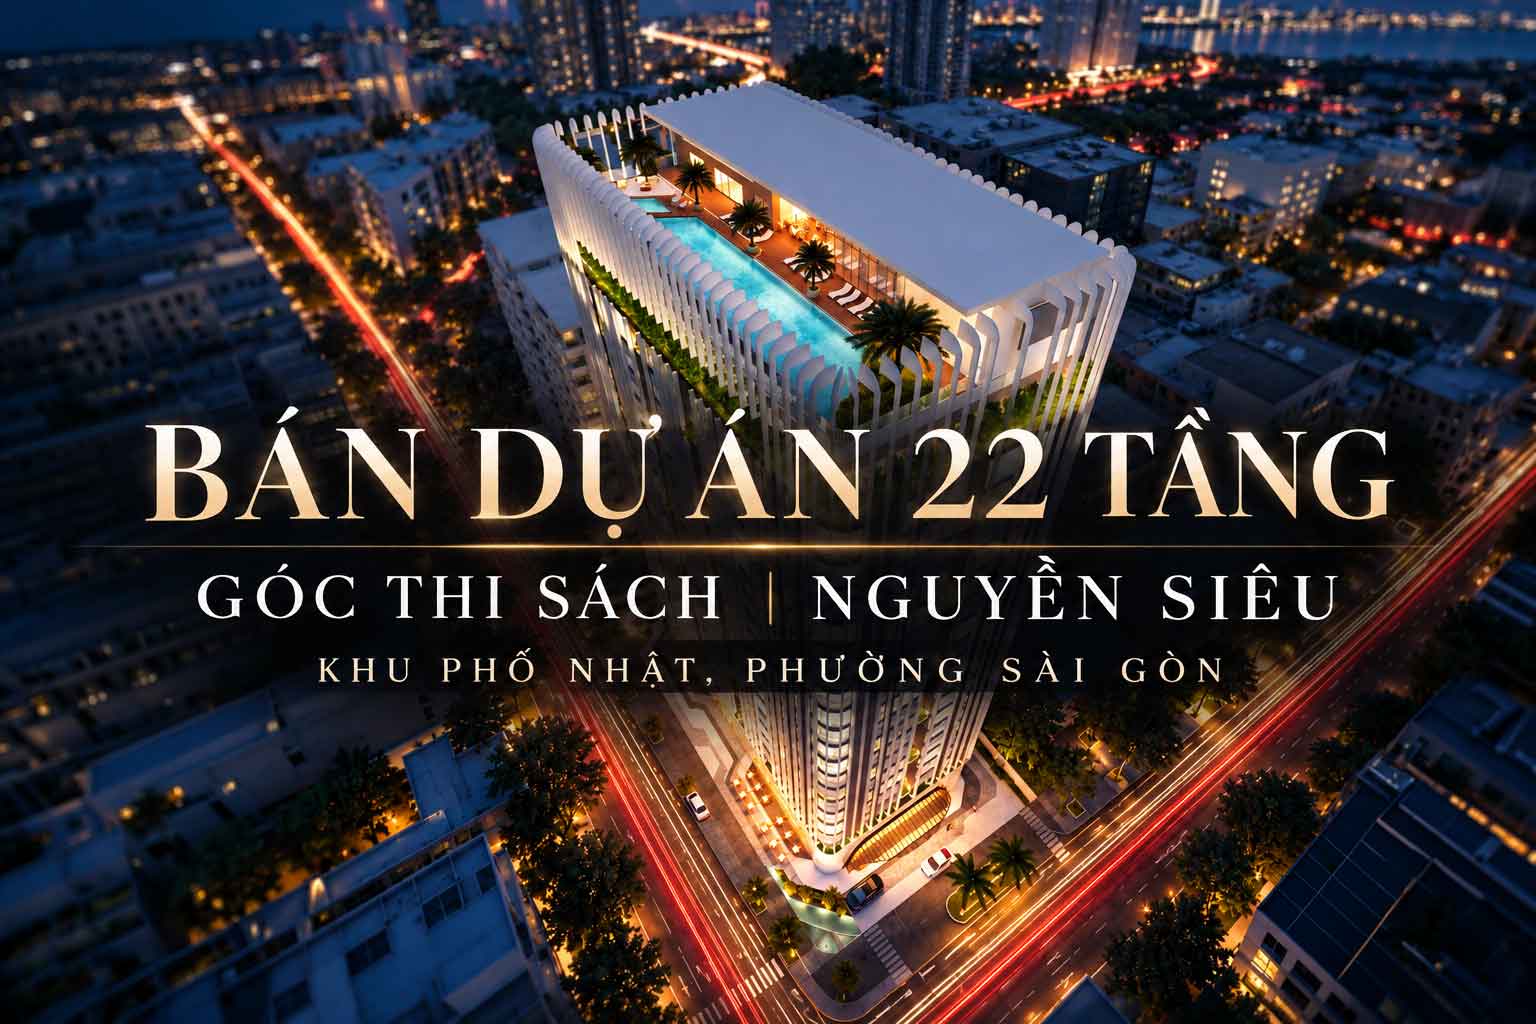
This brief is meticulously curated for the Investment Committees of luxury developers, institutional funds, and corporations seeking formed assets in the CBD. We present project specifications, the 2026 macroeconomic landscape, core residential pricing metrics, acquisition conversion rates, and a reverse-engineered financial model to assess your risk appetite. Strengths are clearly stated; areas requiring stringent appraisal are laid bare.
Executive Summary: This is a premium residential tower featuring 3 basements and 22 upper floors situated on a 2,147 sqm corner plot (Thi Sach – Nguyen Sieu) in Little Japan, Saigon Ward, HCMC. As of October 2026, the bare-shell structural works are completed with fully cleared legalities. It features 162 long-term ownership units and is offered via a 100% corporate share transfer at VND 5,400 billion.
| Item | Specifications |
|---|---|
| Location | Corner of Thi Sach & Nguyen Sieu, core Little Japan area, Saigon Ward (former District 1), HCMC |
| Land Area | 2,147 sqm |
| Scale | 3 basements, 22 upper floors |
| Gross Floor Area (GFA) | 26,978 sqm |
| Current Status | Structural framework completed (Bare-shell) |
| Products | 162 apartments, freehold / long-term ownership |
| Parking | 157 car spaces (approx. 0.97 space/unit) |
| Legal Status | Seller's commitment: fully cleared; ready for sales launch and SPA signing |
| Transaction Structure | 100% equity transfer of the SPV (M&A) |
| Transfer Price | VND 5,400 billion, inclusive of taxes and legal completion |
| Data Room | Legal docs, blueprints, and shareholding structure available upon NDA |
A notable detail from the table: dividing the 26,978 sqm GFA by 162 units yields roughly 166 sqm of construction floor per unit. Such low density signifies a design tailored for large-format apartments, strictly targeting the luxury or ultra-luxury segment — not a mass-market product. Exact Net Saleable Area (NSA) will be verified via blueprints post-NDA.
Executive Summary: The site simultaneously occupies three distinct value layers within HCMC's core: Little Japan, the underground section of Metro Line 1, and the boundaries of the International Financial Center. Finding a 2,000+ sqm dual-frontage plot with residential legalities cleared within this radius is virtually impossible.
The Little Japan enclave hosts a significant concentration of Japanese households, premium restaurants, and spas. The implication for investors is highly pragmatic: expatriates and Japanese executives favor this locale due to CBD office proximity and corporate shuttle access to suburban industrial hubs. This constitutes a long-term, high-yield, and reliable tenant base.
The underground track of Metro Line 1 runs directly beneath Nguyen Sieu Street connecting the Opera House and Ba Son stations. The exact walking distance from the project lobby to the station entrances will serve as a massive premium booster for residential sales.
Encompassing parts of Saigon Ward, the designated International Financial Center is slated for rapid development toward 2027. Saigon Ward will be the primary destination for incoming international finance professionals — a cohort possessing immense purchasing and leasing power for premium apartments adjacent to their offices.
According to current data, the 2026 state-mandated land price framework peaks at VND 325.2 million/sqm along Thi Sach Street. Note that this is purely for calculating state financial obligations and sits significantly below true market transacted values.
Quick Take: The 9-month macroeconomic picture for 2026 presents a duality. Robust growth — HCMC's GRDP hit a 10-year high of 9.06% — and a surge in FDI are highly favorable. However, inflation at 4.7% and mortgage rates hovering above 10% force capital to become highly selective, prioritizing formed, de-risked assets like this project over greenfield developments.
| Indicator (9 Months 2026) | Value |
|---|---|
| HCMC GRDP Growth | +9.06% YoY (~VND 2.46 quadrillion) |
| HCMC Services Sector | +9.27% (Accounting for 51.8% of GRDP) |
| HCMC Average CPI (Inflation) | +4.69% YoY |
| HCMC FDI Inflows | Over USD 17.8 billion |
| Avg. Mortgage Rates (Fixed 12-24m) | ~10.9% p.a. |
Quick Take: According to Q2/2026 reports from Avison Young, luxury segments in HCMC easily exceeded USD 8,000/sqm, while ultra-luxury and branded residences approached USD 18,000/sqm (~VND 470 million/sqm). The average primary price for pre-merger HCMC sat at USD 4,210/sqm according to Knight Frank.
CBD supply is overwhelmingly skewed toward luxury, and central landbanks are essentially finite. In this context, 162 freehold units ready for immediate deployment represent a genuinely rare pipeline. However, value is only unlocked via correct positioning; this asset cannot be marketed at standard "premium" tiers of VND 100-150 million/sqm.
According to JLL Vietnam, the residential sector continues to lead real estate M&A volumes in 2026, with institutional capital strictly prioritizing assets with completed legalities and immediate cash flow potential. The Thi Sach – Nguyen Sieu project perfectly aligns with this criteria.
In September 2025, Malaysia's UOA Group completed the 100% equity acquisition of an SPV owning a 2,000 sqm plot on Vo Thi Sau Street (Tan Dinh Ward) for approx. VND 1,775 billion (~USD 68.27 million).
| Metric | UOA – Tan Dinh (2025) | Thi Sach – Nguyen Sieu (2026) |
|---|---|---|
| Land Area | 2,000 sqm | 2,147 sqm |
| Asset Status | Raw land (Greenfield) | Bare-shell completed (3 basements, 22 floors) |
| Zoning / Product | Grade A Office | 162 Freehold Apartments |
| Transfer Price | ~VND 1,775 billion | VND 5,400 billion |
| Price per GFA sqm | ~VND 89 million/sqm | ~VND 200 million/sqm |
The pricing delta between these two assets must be justified through three variables: the sunk cost of the bare-shell structure, the premium attached to residential freehold sales vs. office leasing, and the immense time-value of money saved by bypassing the legal and foundation-laying phases.
Quick Take: VND 5,400 billion equates to approximately VND 2.51 billion per sqm of land, VND 200 million per sqm of GFA, or VND 33.3 billion per apartment unit. This translates to roughly USD 211 million at the central exchange rate of ~25,610 VND/USD.
| Conversion Metric | Calculation | Result |
|---|---|---|
| By Land Area | 5,400 bil ÷ 2,147 sqm | ~VND 2.51 billion/sqm |
| By Gross Floor Area (GFA) | 5,400 bil ÷ 26,978 sqm | ~VND 200 million/sqm |
| By Apartment Unit | 5,400 bil ÷ 162 units | ~VND 33.3 billion/unit |
| By USD Equivalent | 5,400 bil ÷ 25,610 | ~USD 211 million |
Executive Summary: Merely to recoup the acquisition cost, assuming the Net Saleable Area (NSA) falls between 14,000–18,000 sqm, the average primary selling price must hit VND 300–386 million/sqm (approx. USD 11,700–15,000/sqm), strictly excluding luxury fit-out and SG&A costs. Therefore, the project MUST be positioned in the ultra-luxury or branded residence tier to generate a positive margin.
| Sensitivity Analysis: Gross Revenue minus Acquisition Cost (VND Billions) | ||||
|---|---|---|---|---|
| Assumed NSA | Breakeven Base Price | Sell at VND 350M/sqm (~$13.7k) | Sell at VND 450M/sqm (~$17.6k) | Sell at VND 550M/sqm (~$21.5k) |
| 14,000 sqm | ~386M/sqm | −500 | +900 | +2,300 |
| 16,000 sqm | ~338M/sqm | +200 | +1,800 | +3,400 |
| 18,000 sqm | ~300M/sqm | +900 | +2,700 | +4,500 |
*The positive figures represent the remaining buffer to cover completion costs, sales/marketing expenses (SG&A), financing, and ultimately, net profit.
Acquiring 100% of shares means inheriting the entire enterprise and all associated liabilities. "Fully cleared legalities" is the seller's claim — the buyer's legal team must verify every document, specifically focusing on:
| Investor Group | Strategic Fit | Key Considerations |
|---|---|---|
| Local Luxury Developers | Existing UHNWI client base; bypasses years of legal/foundation hurdles. | Profit margins heavily rely on achieving ultra-luxury pricing. |
| Japanese Corporations/Funds | Located in Little Japan; clear precedents of Japanese capital acquiring SPVs. | Strict 30% Foreign Ownership Limit; cross-border FDI procedures. |
| Regional REITs / Funds | Formed CBD asset aligning with 2026 M&A trends for stable cash flow. | Requires clear exit structuring and currency risk hedging. |
| Branded Residence Operators | Prime CBD location meets all criteria for international hospitality branding. | Rigorous technical standards and high franchise/management fees. |
What is the transaction structure?
A 100% share transfer of the SPV owning the project (M&A). The buyer assumes full control of the entity, the asset, and all associated rights and obligations.
What is the asking price?
VND 5,400 billion, stated to include taxes and completed legalities. This equates to approximately USD 211 million.
What is the construction status?
The bare-shell structure is fully completed, comprising 3 basements and 22 upper floors with a total GFA of 26,978 sqm.
How can we access the Data Room?
The legal dossier, master blueprints, and corporate shareholding structure will be provided strictly after a Non-Disclosure Agreement (NDA) is executed with the authorized seller.
Achieve Realty VN connects institutional investors directly with the authorized mandate. The streamlined process involves four steps: